
UK Shipping and Customs: What you really have to pay
Yes: Shipments from the United Kingdom are generally subject to import duties. Since Brexit, the UK is considered a third country, so import VAT usually applies, and depending on the type of goods, customs duties may also be charged. The basis for calculation is not just the value of the goods themselves, but the total cost of the shipment, including postage. Anyone expecting or planning a shipment from the UK should clarify these points immediately:
- Check the Incoterm at checkout: DDP means the shipper pays the duties, DAP means you pay upon delivery.
- Request a commercial invoice with a full description of goods, value and HS code.
- Clarify whether an EORI number is required for the shipment.
Knowing these three points in advance will help you avoid the most common cause of problems with UK shipping and customs: unexpected additional charges at your doorstep.
Key insights
For UK shipping and customs, the basis of calculation, the value of the goods plus shipping costs, together with the Incoterm, determines who pays which import duties.
| Theme | Details |
|---|---|
| Third country status since 2021 | Great Britain is considered a third country; duty-free access under TCA only applies with proven preferential origin. |
| Assessment basis | Customs duties and import VAT are calculated on the value of the goods plus shipping costs, not on the value of the goods alone. |
| Check Incoterm | DDP means the sender pays duties, while DAP means the recipient pays upon delivery. |
| Keep documents complete | Commercial invoice, HS code, EORI number and proof of origin prevent the most common delays. |
| Automation for businesses | Paket International calculates customs fees in advance and handles customs clearance without manual intervention. |
Table of Contents
- Why UK shipping and customs are treated like a third-country import
- How do you calculate customs duties and import VAT for UK shipments?
- What documents and codes are required for customs clearance in the UK?
- DDP or DAP: Who pays the import duties for UK shipments?
- Three examples of customs duties in the UK
- How companies automate the customs process for UK shipments
- Value limits for goods: What currently applies and what is changing?
- How does customs clearance work for shipments from the UK?
- Where and how is the customs declaration of the goods carried out?
- What are the rules for returns from the EU to Great Britain?
- How do you avoid delays with UK shipping and customs?
- Special rules apply to alcohol, tobacco and food when shipping to the UK
- International Parcel: Automated customs clearance for UK shipments
- Frequently asked questions about UK shipping and customs
- Sources
Why UK shipping and customs are treated like a third-country import
Since January 1, 2021, the UK has been considered a third country for customs purposes. For the EU, it is therefore no longer a single market partner, but a trading partner with its own set of rules. This fundamentally changes how shipments are handled. even if the goods originally come from the EU.
The EU-UK Trade and Cooperation Agreement (TCA) does provide for customs exemption, but this is not automatic. It only applies if preferential origin is proven, meaning that the goods were actually predominantly manufactured in the UK or the EU. If this proof is lacking, the normal third-country customs duties apply, which you can look up in tariff databases such as EZT-Online or the UKGT.
Important: Northern Ireland occupies a special position. Different rules apply to the movement of goods between Northern Ireland and the EU than to shipments from England, Scotland, or Wales, as Northern Ireland remains more closely linked to the EU customs union.
A few things to remember:
- No proof of origin means no customs advantage, no matter how "British" the product appears.
- Proof is usually provided via a declaration of origin on the invoice; for higher values, via REX.
- latest Guidance on preferential arrangements You can find it directly at gov.uk.
Anyone unsure whether a shipment is eligible for preferential treatment should clarify this before sending it, and not only when the shipment is stuck in customs from the UK.
How do you calculate customs duties and import VAT for UK shipments?
The calculation follows a fixed sequence, and anyone who knows this can roughly estimate the total costs before the bill arrives from customs.
- Calculate customs duties, if applicable: The customs duty rate depends on the HS code and is applied to the taxable amount. Without preferential origin, the regular third-country duty rate applies. Customs tariff databases.
- Calculate import VAT: EUSt is not levied on the value of the goods alone, but on the sum of the value of the goods, shipping costs and the customs duty already charged.
- Add up excise taxes, if applicable: For alcohol, tobacco, or certain luxury goods, additional excise taxes are added, separate from customs duties and EUSt.
The HS code is the crucial factor here. Two almost identical products can trigger completely different customs duties due to an incorrect coding. Therefore, it's worth taking a look at the HS code. EZT-Online or the British UKGT database before the invoice is generated, not afterwards.
Pro tip: Always calculate EU VAT only after the customs duties have been determined. Reversing the order almost always leads to an underestimation of the total tax by several percentage points.
What documents and codes are required for customs clearance in the UK?
Without the correct documentation, every shipment will get stuck in UK customs and shipping, no matter how accurately the goods themselves are declared. Four documents are crucial for a smooth process:
- Commercial invoice: A complete description of the goods, quantity, value, currency, Incoterm and country of origin must be included, otherwise customs will request further information.
- HS code: This determines the customs duty rate and, in some cases, whether special regulations apply. Incorrect codes are the most frequent cause of delays in the customs clearance process.
- EORI number: It is required for commercial shipments above a certain value; private individuals generally do not need it.
- Proof of origin: For higher-value goods, a simple explanation on the invoice is often insufficient; REX registration is then required.
Anyone who regularly imports to or exports from the UK should... Determine customs tariff number Go through the process thoroughly once and document it, instead of researching anew for each broadcast.
Pro tip: Experienced exporters use special customs procedures such as the so-called Procedure 42 to avoid import VAT in third countries and conserve liquidity. However, for occasional private imports, the effort is hardly worthwhile.
DDP or DAP: Who pays the import duties for UK shipments?
The Incoterm used at checkout determines who ultimately receives the invoice from customs, and this is far too often overlooked.
For DDP (Delivered Duty Paid) means the sender covers all import duties and delivers the goods "fully cleared" right to your door. You pay nothing extra. DAP or the older DDU (Delivered at Place or Duty Unpaid) the recipient pays customs duties and import VAT, which are usually collected by the parcel service upon delivery, often along with an additional customs clearance fee.
For private customers, this is the crucial difference between a smooth purchase and an unpleasant surprise. Therefore, here are some practical tips:
- Before buying, check whether the shop offers DDP or DAP; this is often stated in the fine print of the shipping conditions.
- British shops are sometimes required to adhere to special postage regulations for low-value goods, but this does not automatically exempt them from courier fees.
- In B2B business, the Incoterm is usually specified in the sales contract; therefore, a clear agreement before the first delivery is advisable.
- Couriers like DHL or DPD often charge a fixed service fee for customs clearance on DAP shipments, in addition to customs duties and EU VAT.
Retailers who offer DDP demonstrably reduce returns because customers do not experience unexpected costs.
Three examples of customs duties in the UK
Numbers speak louder than any explanation. Three typical cases show how differently the tax burden varies when shipping to the UK.
- Small private purchase, goods value €60, shipping €8: The tax base is €68. For low-value goods, the old exemption limit may still apply in some cases, but the general rule is: as soon as import VAT is due, it is calculated on the full amount including shipping, not just on the value of the goods. In this example, the import VAT is typically around 19% of €68, i.e., about €13.
- Average order value: €180 plus €15 shipping: The tax base is €195. Without preferential origin, customs duties are first calculated on €195, let's assume a 4% customs rate for this product, i.e., €7,80. The import VAT is then levied on €202,80 (value of goods plus shipping plus customs duties).
- Commercial delivery with proven preferential origin, goods value €800: If a valid declaration of origin is provided, customs duties are completely waived under the TCA. Only import VAT on the value of the goods plus shipping costs remains, however, with the administrative effort of correctly documenting the proof of origin and being able to present it upon inspection.
These three cases illustrate the crucial difference: Proof of origin can amount to several dozen euros for larger shipments, while it is hardly noticeable for small private shipments.
How companies automate the customs process for UK shipments
Anyone who regularly ships to or from the UK quickly reaches the limits of manual customs clearance. Checking each shipment individually, manually assigning HS codes, and answering customs inquiries takes time that is then lacking in day-to-day operations.
Automated platforms calculate customs duties and import VAT before shipment, automatically compare HS codes with product databases, and transmit the customs declaration directly to the relevant systems. This significantly reduces queries, as confirmed by Chamber of Industry and Commerce (IHK) practical guidelines on automation in cross-border shipping.
Paket International takes care of exactly these tasks in an automated process: Shipping costs and customs fees are calculated in advance, customs clearance is carried out without manual paperwork, and a dashboard shows the status of each shipment at any time.
When choosing such a solution, it is worth considering four points:
- API integration into existing ERP or online shop systems
- Automatic matching of HS codes with product data
- Support for proof of preferential origin
- Transparent reporting across all broadcasts
Pro tip: Before switching providers, check whether automated data checks Actually reducing customs inquiries is the measurable advantage over manual processing.
Value limits for goods: What currently applies and what is changing?
The €150 limit was long the key threshold for UK shipping and customs: up to this value, no customs duties were levied, only import VAT. However, this rule is currently under discussion. Consumer advice center points this out, that changes to this threshold may be planned, including a possible abolition of the exemption limit.
This means that you shouldn't assume the €150 limit will remain in its current form indefinitely. Anyone who regularly orders or sells from the UK should check the current regulations before each large shipment, instead of relying on experience from last year.
It's also important to distinguish between the customs duty threshold and the obligation to pay import VAT. Import VAT can generally be levied on goods valued at as little as one euro, while the customs duty exemption below €150 only applies to customs duties themselves, not the VAT. Many buyers confuse these two thresholds and are then surprised to receive a subsequent import VAT demand, even though the value of the goods was below the supposed "exemption threshold".
For planned commercial imports of larger volumes, it is also worth taking a look at the current thresholds for collective declarations, as different reporting obligations may arise depending on the shipment volume.
How does customs clearance work for shipments from the UK?
Since Brexit, every shipment from the United Kingdom goes through a fixed process before reaching its recipient in the EU. The parcel is registered for customs purposes at the first point of entry into the EU, usually automatically via the electronic customs declaration of the parcel service.
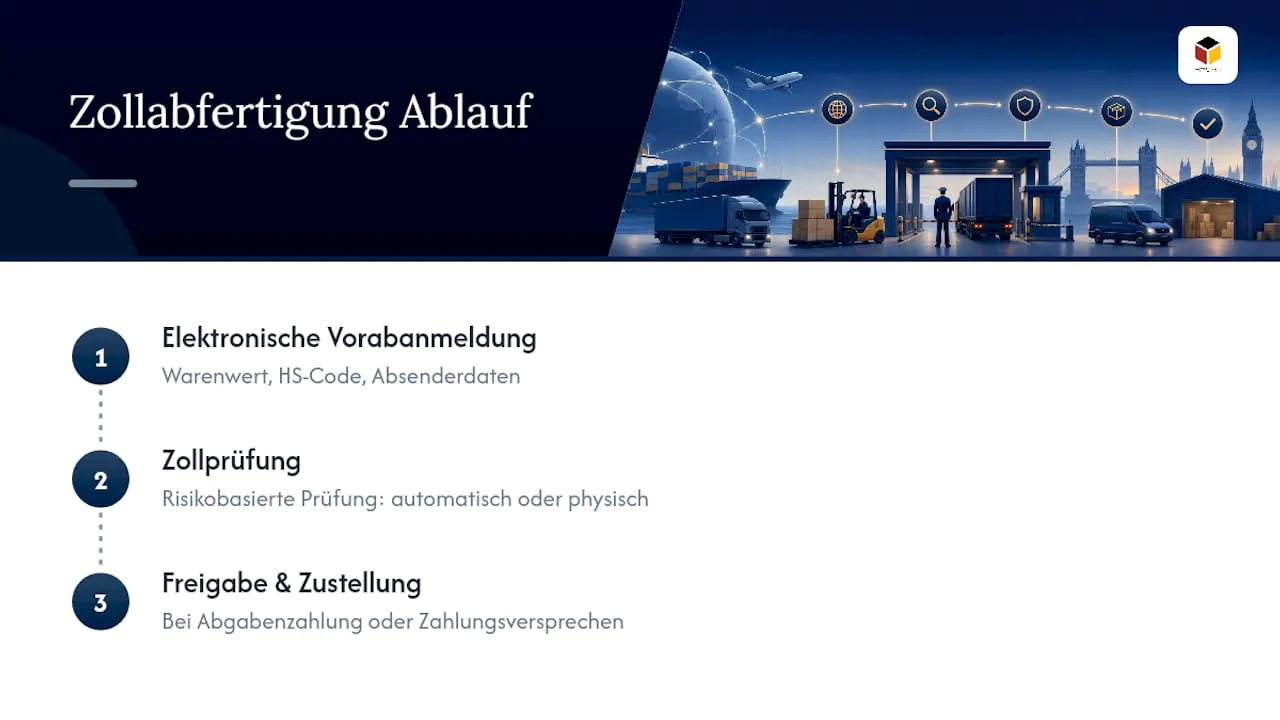
The process is roughly divided into three steps: First, the electronic pre-declaration, in which the value of the goods, HS code, and sender data are transmitted. Second, the inspection by customs, which can be carried out automatically or with physical inspection depending on the risk classification. Third, the release for delivery as soon as duties have been paid or a payment guarantee from the parcel service is received.
Experienced shippers use special customs procedures to expedite processing or optimize tax treatment. Customs clearance often takes place at the first EU entry point, but procedures such as the so-called Procedure 42 can, under certain conditions, result in a tax-advantageous intra-Community supply, as described in practical advice from the Stuttgart Chamber of Industry and Commerce.
For private individuals, this process is usually invisible, running in the background via the parcel service. However, for companies with regular goods traffic, a closer look at the chosen methods is worthwhile, as they directly affect liquidity and processing time.
Where and how is the customs declaration of the goods carried out?
In Germany, customs declarations are processed via the electronic ATLAS system, which is operated by the German customs administration for import and export. For postal shipments, in practice, the parcel service or a customs service provider commissioned by them usually handles this declaration on behalf of the recipient.
For smaller private shipments, the registration process is often simplified: The parcel service registers the value and type of goods based on the commercial invoice, customs automatically calculates the duties due, and the recipient receives a payment request before the shipment is delivered.
For commercial shipments with a higher value, the declaration process becomes more detailed. This generally requires an EORI number for the recipient, a complete commercial invoice with HS code, and, if applicable, proof of origin. If any of this information is missing, customs will hold the shipment and request the missing documents, which can delay delivery by several days.
Those who don't want to leave the customs declaration to the parcel service can also have it done themselves via a customs broker or specialized software. For companies with regular shipment volumes, this is often the more efficient solution because the data is already structured in advance and doesn't have to be checked only upon arrival of the shipment.
What are the rules for returns from the EU to Great Britain?
Returns for UK shipments aren't simply a reversal of the original shipment; they're subject to their own set of rules, which many retailers underestimate. From a customs perspective, a return from the EU to the UK is considered both an export from the EU and an import into the UK.
For returned goods, it is crucial whether the goods originally originated in the UK. If the sender can prove that the returned goods were indeed previously imported from the UK, a renewed duty can often be avoided, provided the corresponding documentation is available. Without this documentation, UK customs may treat the return as a regular new import, incurring new customs duties and taxes.
For online retailers in the EU who sell to British customers, this means: Returns processes should be considered from the outset, not just when the first return arrives. Clearly marking the item as returned on the invoice and retaining the original import documents significantly simplifies the process.
In practical terms, this means for retailers: Anyone offering DDP shipping should also design their returns logistics accordingly, so that the customer is not suddenly confronted with customs formalities when making a return, which they never saw during the original purchase.
How do you avoid delays with UK shipping and customs?
Most delays in the customs clearance process are not caused by complicated rules, but by missing or incorrect basic information. A few structural habits can prevent the majority of these problems.
- Always fill out commercial invoices completely, including a clear text description of the goods instead of just the item number.
- Verify the HS code once before shipping; do not copy it from an old shipment, products change.
- State the value of goods realistically; undervalued shipments are noticed during random checks and result in more detailed inspections.
- Check the EORI number for commercial shipments in advance, not just when customs asks for it.
- Clarify the Incoterm with your business partner in advance so that it is clear who to contact if you have any questions.
Especially for recurring shipments, a one-time, thorough documentation of the standard information is worthwhile. By correctly defining the HS code, rules of origin, and invoice template once, you avoid having to recreate them for every new shipment and permanently reduce the risk of errors.
Special rules apply to alcohol, tobacco and food when shipping to the UK
Certain categories of goods are subject to additional regulations for shipments between the UK and the EU, which go beyond the normal customs and import VAT calculations. Anyone shipping these categories should inform themselves more thoroughly beforehand than with ordinary consumer goods.
Alcohol and tobacco In addition to import VAT, they are also subject to excise duty, which is levied independently of the customs duty. For private individuals, stricter quantity limits often apply than for other product categories, and shipping by mail is frequently restricted or prohibited anyway, as alcohol and tobacco are often classified as hazardous goods or restricted items within the shipping network.
Food products They are also subject to veterinary and plant protection controls. Animal products such as meat or dairy products often require specific permits and health certificates, without which import into the EU is generally prohibited. This applies regardless of the value of the goods and even for small quantities in private luggage or parcel shipments.
Commercial shippers of these product categories are strongly advised to consult with a specialized customs service provider before their first shipment, as requirements vary significantly depending on the product category and violations can lead to delays and even the destruction of the shipment. If you are unsure about the specific classification, it is advisable to contact your local Chamber of Industry and Commerce (IHK) or customs directly before shipping the goods.
International Parcel: Automated customs clearance for UK shipments
For companies that regularly handle shipments between the EU and the UK, manual customs processing is the biggest time-waster in the entire shipping process. Creating each commercial invoice individually, manually checking each HS code, answering each customs inquiry individually: this consumes resources that are then lacking in day-to-day operations.
Paket International automates these tasks. The platform connects systems, parcel services, and customs services in a single process, allowing shipping costs and customs duties to be calculated in seconds before a shipment even leaves the warehouse. Automatic customs clearance operates without manual intervention, significantly reducing administrative effort and thus costs in the shipping process. A central dashboard displays the status of each shipment at any time, including the calculated import duties.
Those who wish to transparently display UK customs fees at checkout will find a suitable solution at Calculate import duties at checkoutFor a direct introduction to automated shipping processing, it's worth taking a look at the International shipping with professional customs clearance, where you can configure the right solution for your shipping volume.
Frequently asked questions about UK shipping and customs
Are import duties automatically levied on every shipment from the UK?
Not always. If preferential origin is proven, customs duties are waived, but import VAT is usually levied regardless, as soon as the value of the goods plus shipping costs exceeds a relevant threshold.
Who pays the customs fees, the buyer or the seller?
That depends on the Incoterm. With DDP, the seller covers all duties and taxes; with DAP or DDU, the buyer pays upon delivery, often along with a customs clearance fee charged by the parcel service.
What happens if the HS code on the invoice is incorrect?
Customs may hold the shipment and demand a correction, which significantly delays the delivery process. In some cases, an incorrect, usually higher, customs duty rate is also applied until the correction is made.
Does the €150 limit for UK shipping still apply?
For larger shipments, do not rely solely on this threshold; check the current regulations before shipping.
Do I need an EORI number for private UK orders?
Generally not. The EORI number is mainly required for commercial shipments; private individuals usually get through customs clearance without it.
Sources
For a precise review of tariffs and current regulations, it is worthwhile to consult official sources directly:
- Brexit: Trade in goods from 2021 onwards – Chemnitz Chamber of Industry and Commerce
- Customs and preferential origin – European Commission